
Platinum-group metal
RutheniumA specialist metal in the data economy.
Ruthenium serves electronics, magnetic data storage and chemical catalysts, with additional semiconductor uses under development. Its production follows the wider platinum-group supply chain, while each new application needs to translate into actual material demand.
Explore the case ↓ Ru
- Material
- Ru
- Key uses
- Electronics, data storage and catalysts
- Supply to understand
- Platinum-group mining by-product
On this page +
Ruthenium in detail
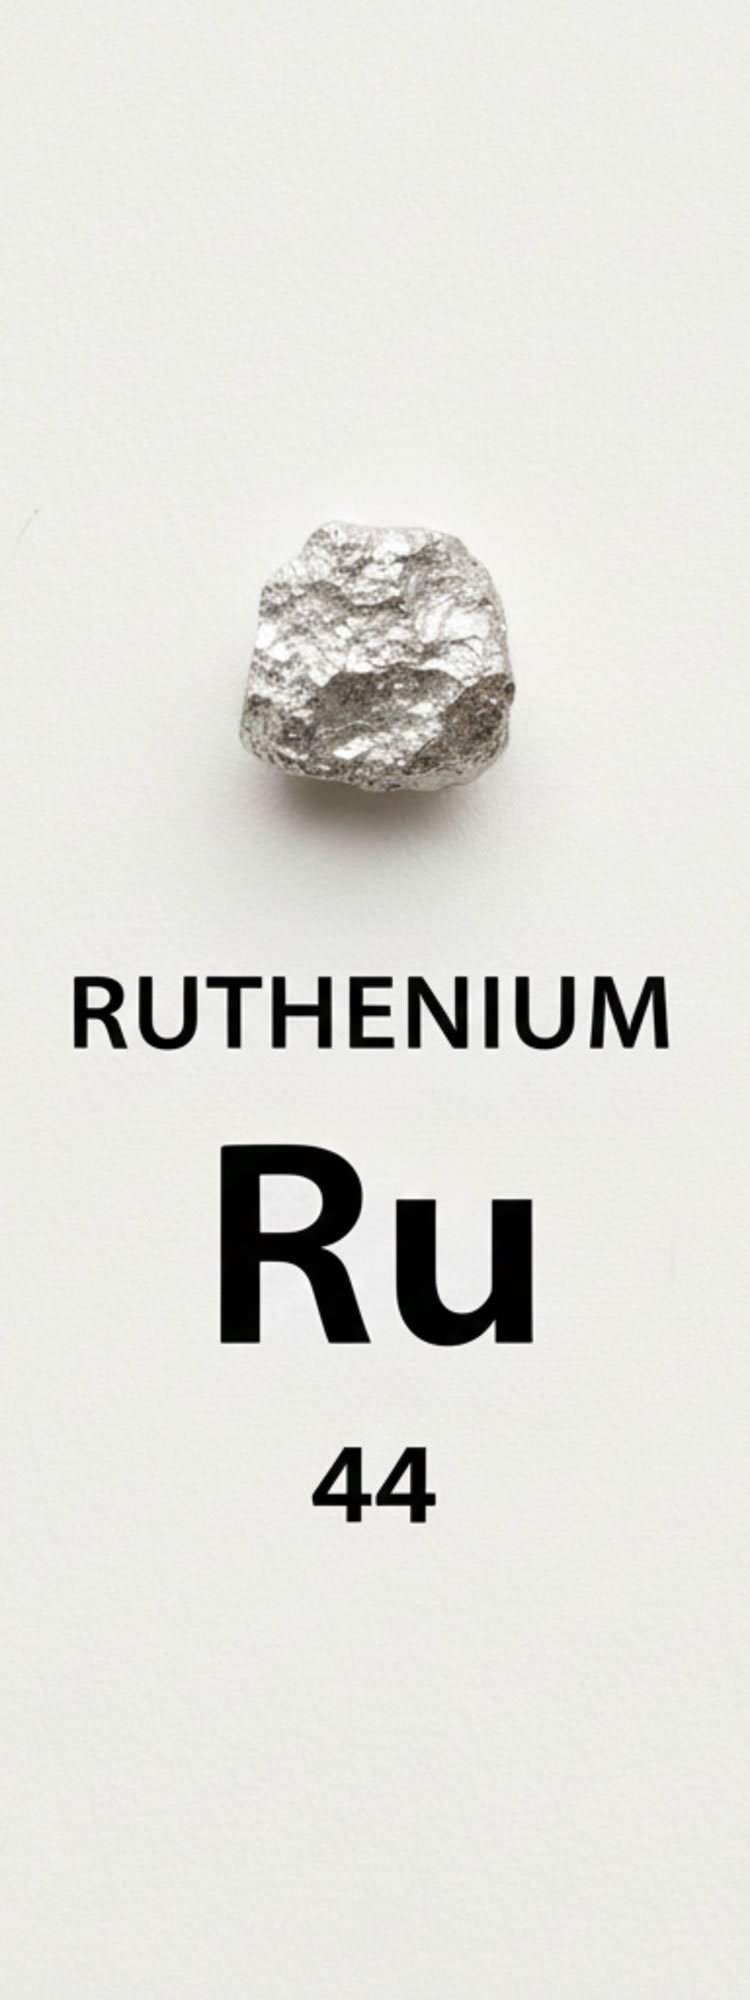
Ruthenium is a rare metal with multiple industrial uses. It is known for its excellent hardness, corrosion resistance, and unique electronic properties. Primarily used in the electronics industry, it plays a crucial role in chip resistors, hard disk drives, and advanced semiconductor applications. Additionally, ruthenium is vital in chemical catalysts, fuel cells, aerospace superalloys, and high-durability electrical contacts, benefiting from its high melting point (~2334°C) and wear resistance.
Supply remains constrained as ruthenium is obtained only as a byproduct of platinum and nickel mining, primarily sourced from South Africa, Russia, and Zimbabwe. Geopolitical tensions, mine disruptions, and refining bottlenecks contribute to supply risks and price volatility, making ruthenium a compelling yet speculative investment opportunity in the strategic metals sector.
Why Invest in Ruthenium?
Ruthenium is a platinum-group metal (PGM) essential to advanced semiconductor manufacturing – particularly sub-3nm logic interconnects and next-generation DRAM – as well as chip resistors, magnetic data storage, chemical catalysis, and hydrogen electrolyzers. With annual production below 30 tonnes globally, demand from semiconductor fab expansions, automotive electronics proliferation, and emerging hydrogen infrastructure is tightening an already constrained market.
Supply concentration poses material risk: approximately 70% of ruthenium originates from South African PGM operations and 20% from Russia’s Norilsk complex. As a byproduct metal extracted at 0.001-0.01 ppm concentrations from platinum ores, production responds sluggishly to price signals – primary mining economics prioritize platinum and palladium, not ruthenium. Geopolitical friction, sanctions exposure, and South African operational disruptions create persistent supply uncertainty.
For investors, ruthenium represents extreme exposure to technology miniaturization trends with no supply elasticity. This is a small, illiquid market underpinning critical semiconductor roadmaps at TSMC, Samsung, and Intel – delivering significant upside potential alongside commensurate volatility, storage complexity, and exit liquidity constraints.
Book a free 15 minute call with an Earth Rarest expert
Ruthenium Price Trends
Who produces ruthenium?
Ruthenium Demand and Market Outlook
View Sources (6)
- https://single-market-economy.ec.europa.eu/sectors/raw-materials/areas-specific-interest/critical-raw-materials_en
- https://www.ukcmic.org/downloads/reports/ukcmic-2024-criticality-assessment.pdf
- https://pubs.usgs.gov/periodicals/mcs2024/mcs2024-platinum-group.pdf
- https://www.fortunebusinessinsights.com/ruthenium-market-108084
- https://pubs.rsc.org/en/content/articlelanding/2024/ta/d4ta02337d
- https://passive-components.eu/resistor-markets-tighten-as-ruthenium-prices-skyrocket/

 | Thank you for Signing Up |

How to Invest in Ruthenium
Unlike gold or silver, there is no large, exchange-traded market for ruthenium. Pricing is set in a small over-the-counter network of refiners and specialist dealers, often using base prices from firms such as Johnson Matthey and a handful of price-reporting services. Retail access is limited, spreads are wider than in mainstream precious metals, and price discovery is relatively opaque for private investors compared with the transparent spot markets for gold, silver or even platinum.
The most common indirect route into ruthenium is via equities that mine or refine platinum-group metals. Producers such as Anglo American Platinum, Impala Platinum, Sibanye-Stillwater or Norilsk Nickel earn a portion of their revenue from ruthenium output, but their share prices are driven mainly by platinum, palladium and rhodium cycles, as well as broader corporate factors like operating costs, capital spending and balance sheet strength rather than the ruthenium price alone. In practice, this means an investor is buying a diversified PGM and mining business, not pure ruthenium exposure.
Direct Invest
For investors who want direct exposure, buying high-purity ruthenium bars or ingots from specialist strategic metals dealers is the primary option. Because ruthenium is a byproduct metal with a tiny, dealer-driven market, spreads and liquidity risk are significant, so professional storage in secure, insured vaults is strongly preferred over home storage. Using bonded facilities with proper documentation and chain-of-custody records helps with future resale, since industrial buyers and wholesalers typically require clear proof of origin and purity before they quote a buyback price.
As a critical material for advanced electronics, data storage, chemical catalysts and emerging hydrogen technologies, ruthenium represents a focused but highly specialised investment theme. Its supply is constrained by its role as a minor byproduct of PGM mining and by the geographic concentration of production, while demand is increasingly tied to AI data centres, high-end resistors, semiconductor processes and electrolysers. That combination – small market size, constrained supply and growing industrial reliance – makes ruthenium a potentially powerful, but high-volatility, way to target the long term growth of the digital and clean energy economies.
Buying Ruthenium with Us ($10,000 Minimum)
We organise the sourcing of investment grade ruthenium, secure insured storage in professional vaults, and the eventual liquidation of your position when you decide to exit, giving you a streamlined end-to-end service. The metal remains your property at all times while we handle procurement, logistics, custody and resale, so you can gain targeted exposure to ruthenium without having to build your own specialist relationships with refiners, vault operators and industrial buyers. Our minimum ticket size is $10,000, which reflects the niche nature of the market and helps keep storage and transaction costs efficient relative to the size of your position.
* Not financial advice. Industrial metal buying is not a regulated investing space.
Book a free 15 minute call with an Earth Rarest expert
Looking to buy Ruthenium for Industrial usage?
This page is focused on Ruthenium as an investment asset (buy and hold). For industrial purchase of Ruthenium please, click here.
Before you decide
A useful thesis has a question behind it.
Which semiconductor uses are already buying material, and which remain on a development roadmap?
Use the research above to test the case. Then check the exact material, purity, available quantity and resale terms against a dated quote.
Explore the price evidence →Follow the connections
No metal exists in isolation.
Iridium →
Iridium has a role in PEM electrolysers as well as demanding industrial components. Recovery within the wider platinum-group mining chain limits how directly its production can respond to interest in hydrogen technology.
Gallium →
Gallium compounds serve power electronics, radio-frequency devices and LEDs. Production is largely tied to aluminium and zinc refining, making recovery and processing capacity central to the supply story.
Platinum →
Platinum's appeal centres on constrained supply and a broad set of industrial uses. Repeated annual deficits make stocks worth watching, while recycling, investment flows and demand changes can alter the balance.
Who can supply the world? ↗
Compare the countries and supply chains behind the materials.
Inside the technology ↗
Explore the materials that make semiconductors work.
From research to ownership ↗
Understand buying, storage and the practical steps.
A conversation, when you’re ready
Turn your interest into a clearer plan.
Tell us which metals caught your attention. We’ll help you explore availability, the buying process and what ownership would involve.